

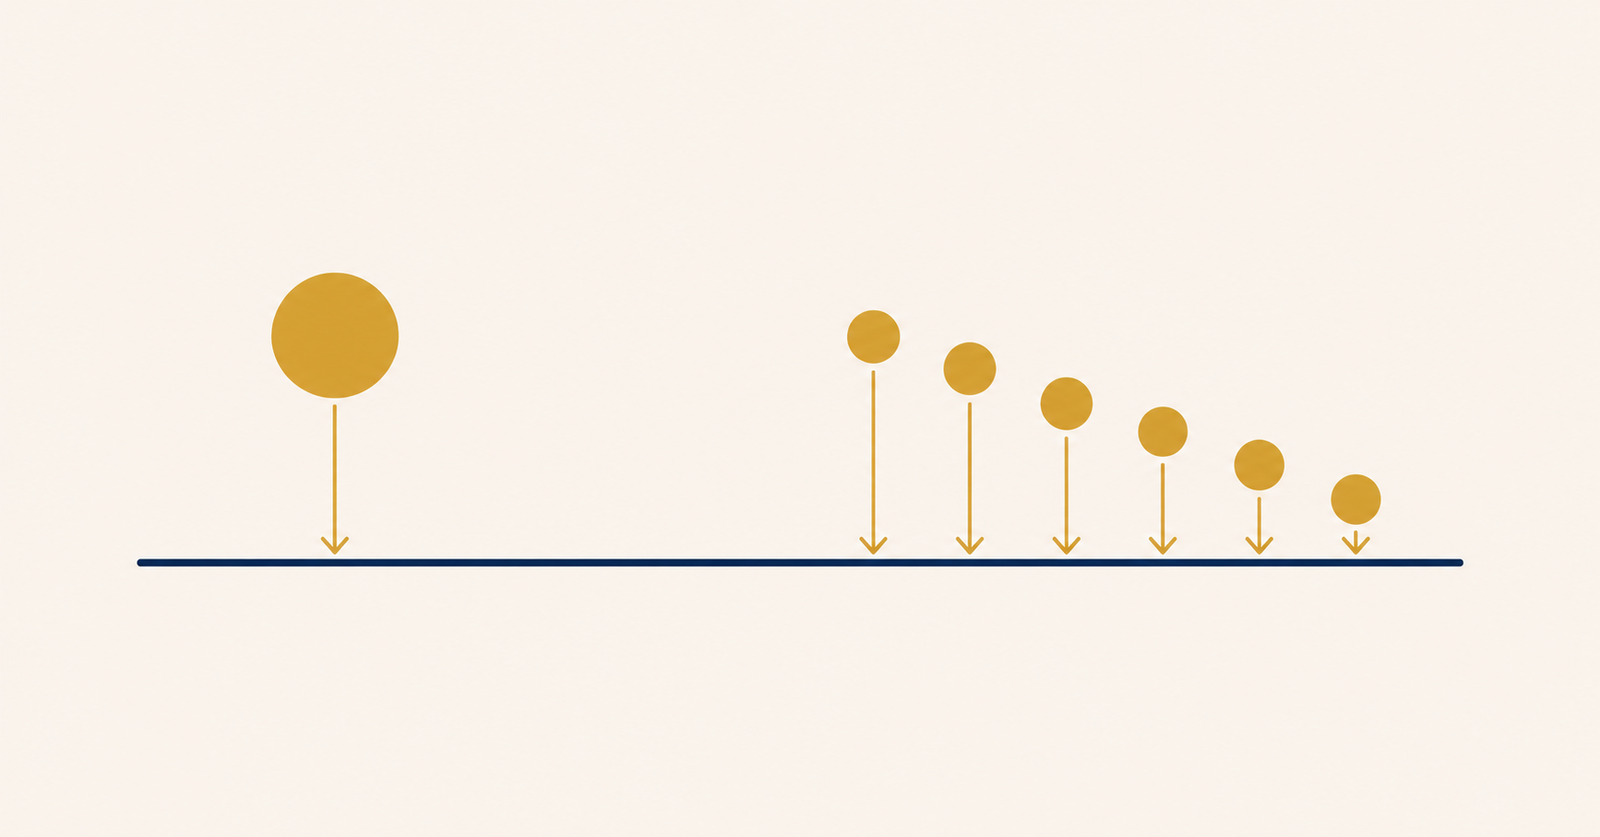
Sailing income doesn’t arrive as a steady monthly paycheck — it arrives in chunks, usually a real amount landing all at once at the end of a contract. When that happens, the question isn’t really “should I invest it” — it’s lump sum vs SIP: put it all in now, or spread it out over time?
Lump sum vs SIP: why investing it all now tends to win more often
Across long stretches of market history, investing a lump sum immediately has outperformed spreading the same amount out over time in more than 60% of periods studied — the simple reason being that markets trend upward more often than they fall, so money that’s invested sooner spends more time compounding in a rising market than money held back and drip-fed in later. This is the same “time in the market beats timing the market” logic behind the power of compounding — every month spent deciding rather than invested is a month of growth that’s gone for good.
Why the other 40% is exactly what makes people hesitate
Odds favouring lump sum on average doesn’t make the other outcome imaginary — investing everything right before a downturn is a real possibility, and it stings in a way that missing out on some upside never quite does. That asymmetry, where a loss feels worse than an equivalent gain feels good, is exactly why staggered entry still has genuine appeal even when it isn’t the statistically stronger choice on average. It’s also why so many lump sum investors who got the timing wrong ended up panic-selling near the bottom instead of riding it out — the size of the initial commitment made the drop feel more urgent to escape.
STP: the practical middle path for money that arrives all at once
A Systematic Transfer Plan solves the actual problem most sign-off payouts create: the money shouldn’t sit idle in a savings account while you decide, but committing all of it to equity in one move can feel like a lot at once. An STP parks the full amount in a liquid or debt fund immediately — so it’s earning something from day one instead of nothing — then automatically moves a fixed amount into an equity fund on a set schedule, monthly for instance, over a period like 6 to 12 months. It’s effectively a SIP built from a lump sum that’s already arrived, rather than one built up gradually from future income.
What actually matters more than winning this particular debate
For a payout headed toward a goal that’s still years or decades away, lump sum and STP converge to roughly the same place once enough time has passed — the entry method matters far less than simply getting the money invested rather than left sitting in a savings account earning next to nothing. Worth deciding based on how much regret risk you’re comfortable carrying, not on chasing the theoretically optimal answer — and worth checking first that your sign-off buffer is already covered before any of this payout goes toward investing at all.
AMFI’s investor education material covers both approaches in more depth if you want to see the mechanics laid out further before deciding.
This post is general education and does not constitute personalised advice. As an AMFI-registered Mutual Fund Distributor (ARN 185676), we help clients decide how to deploy a contract-end payout in a way that actually fits their goals and comfort with risk. See our Retirement Planning page or get in touch to talk through yours.
More From The Log
